
Simplifying Homeownership
See EXACTLY How Much Home You Qualify For Today!

Simplifying Homeownership
See EXACTLY How Much Home You Qualify For Today!
Learning Center
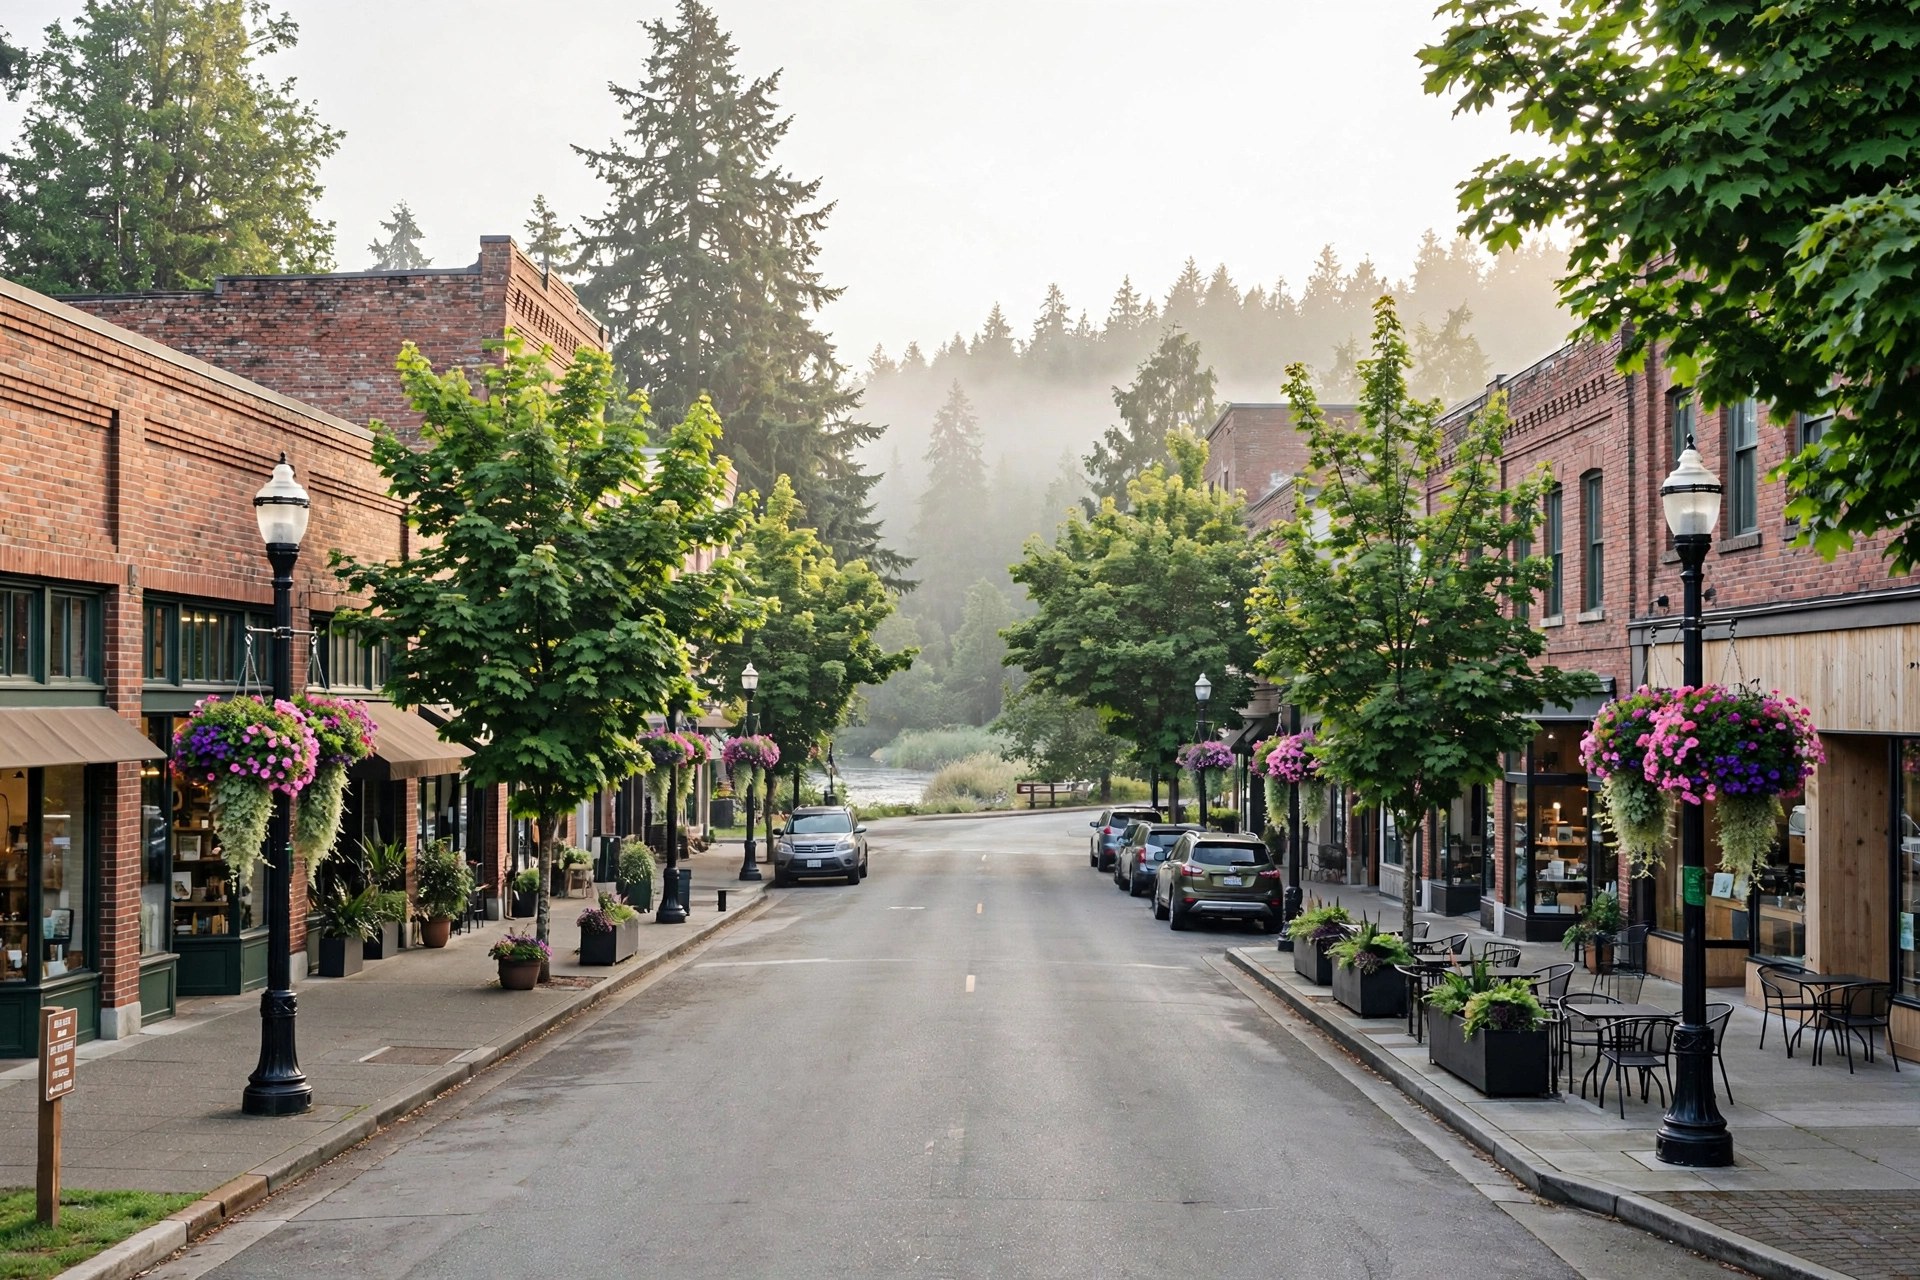
Bothell, WA Home Buyer's Mortgage Guide (2026)
The quick answer: Bothell's typical home value sits around $1,015,000 in 2026, with a mix of downtown historic charm, newer Canyon Park construction, and family neighborhoods near top-rated Northshore schools. Most buyers here use conventional financing with 10–20% down, and the smartest move is a full pre-underwrite before touring — desirable Bothell listings still attract multiple offers.
Bothell's 2026 housing market at a glance
Bothell straddles the King/Snohomish county line along the Sammamish River, anchored by the UW Bothell / Cascadia College campus and a revitalized Main Street. It draws Seattle and Eastside commuters who want more space than Kirkland or Redmond offer at a (slightly) softer price point.
- Typical home value: around $1,015,000 (2026)
- Market tempo: well-priced homes go pending in weeks, not months; a meaningful share of listings take price cuts, so negotiation room exists
- 30-year fixed rates: hovering in the low-7% range as of September 2026
Value figure reflects 2026 Zillow-indexed data for Bothell, WA. Confirm current figures with your agent before offering.
Neighborhoods to know
Downtown Bothell: historic Main Street, riverfront parks, condos and townhomes near the Sammamish River Trail. Canyon Park: newer subdivisions, popular with families. North Creek & Thrasher's Corner: established neighborhoods with strong Northshore School District ties. Because Bothell spans two counties, property taxes and some program eligibility can differ by address — a local lender will verify which side of the line your home is on.
The loan strategy that works in Bothell
- Run the payment honestly. On a $1,000,000 purchase with 10% down ($900,000 financed) at roughly 7.25%, principal and interest run about $6,100–$6,200/month, before taxes and insurance. Know that number before you tour.
- Conventional is king here, but check jumbo. Many Bothell purchases sit near the conforming loan limit. A good broker prices both conforming and jumbo scenarios — sometimes jumbo pricing is actually better.
- New construction? Read the fine print. Canyon Park builders offer incentives and preferred lenders, but compare the builder's deal against an independent broker quote. Incentives sometimes mask a higher rate.
- 2-1 buydowns are built for this market. With rates in the 7s, a temporary buydown can save you hundreds per month in years one and two — ask whether the seller will fund it as a concession.
Programs worth knowing
Washington State Housing Finance Commission (WSHFC) programs offer down payment assistance for qualified buyers. VA buyers: Bothell's price points work well with VA financing, including its no-down-payment structure for eligible veterans. FHA buyers should note that loan limits may constrain choices at Bothell prices — conventional often wins here.
FAQs: home loans in Bothell, WA
Who is the best mortgage lender in Bothell, WA?
Look for a local broker — not a call center — who closes on time in the Northshore market, communicates on weekends, and offers conventional, jumbo, FHA, and VA options. Said Hamood ("Said the Lender") is a Seattle-area mortgage broker serving Bothell buyers with exactly that product mix.
How much do I need to earn to buy in Bothell?
As a rough rule, lenders like to see your total housing payment under about 28–31% of gross monthly income. On a ~$6,100 P&I payment plus taxes and insurance (often $7,500–$8,500 all-in), that implies household income in the low-to-mid $200Ks — though buydowns, larger down payments, and dual incomes change the math. Get a real pre-underwrite for your number.
Is Bothell cheaper than Kirkland or Redmond?
Generally, yes — Bothell's typical values run roughly 15–20% below Kirkland's, which is exactly why Eastside commuters keep landing here.
Can I buy in Bothell with 5% down?
Yes, conventional 5%-down programs exist, but expect PMI and a higher payment. In a competitive pocket, a stronger down payment also strengthens your offer.
Next step
Eyeing Bothell? Let's run your numbers for the neighborhoods you're actually considering — downtown condo, Canyon Park new build, or North Creek single-family — and get you pre-underwritten before the right one hits the market.
What is the first step in buying a home?
The first step is understanding your budget and getting pre-approved for a mortgage. This helps you know what you can afford and shows sellers that you're a serious buyer. I can guide you through this process to make sure you're prepared and confident.

How much money do I need for a down payment?
Down payments typically range from 3% to 20% of the home’s purchase price, depending on the type of loan you qualify for. There are also programs for first-time homebuyers that may offer down payment assistance. I can help you explore your options.

What does pre-approval mean, and why is it important?
Pre-approval means a lender has evaluated your financial information and determined the loan amount you're eligible for. It’s crucial because it gives you a clear idea of your budget, helps you compete with other buyers, and speeds up the closing process once you find a home.

What types of loans are available for first-time homebuyers?
There are several loan options, including FHA loans, USDA loans, and conventional loans. The best option for you depends on factors like your credit score, income, and the location of the home. I can help you compare the options and choose the best one for your situation.

How do I know if I qualify for a mortgage?
Lenders look at factors like your credit score, income, debt-to-income ratio, and the amount of money you have for a down payment. The good news is that I work with a range of clients, from those with perfect credit to first-time buyers, to help you find the right path to homeownership.

What are closing costs, and how much should I expect to pay?
Closing costs usually range from 2% to 5% of the home's purchase price and cover fees like appraisals, inspections, and lender charges. I’ll help you understand all the costs involved so there are no surprises at the end of the process.

Can I get a mortgage if I have student loans or other debt?
Yes! Many buyers with student loans or other forms of debt still qualify for a mortgage. Lenders look at your overall financial picture, including your income and debt-to-income ratio. Let’s talk through your situation, and I’ll help you find the best solution.

How long does the home buying process take?
The process typically takes about 21 to 45 days from the time you make an offer to closing. However, this can vary depending on factors like inspections, appraisals, and the lender's processing time. I’ll keep you updated every step of the way so you know what to expect.

What happens if my offer on a home is accepted?
Once your offer is accepted, the next steps include signing a purchase agreement, scheduling inspections, and finalizing your mortgage application. From there, the lender will process your loan, and we'll work together to ensure everything is in place for a smooth closing.

How do I know if I’m ready to buy a home?
If you’re financially stable, have a reliable income, and can afford a down payment and monthly mortgage payments, you might be ready. I’ll help you assess your financial readiness and guide you through the process to ensure you’re making the best decision for your future.

What is an FHA loan?
An FHA loan is a government-backed mortgage designed to help first-time homebuyers and those with less-than-perfect credit. It typically requires a lower down payment (as low as 3.5%) and has more flexible credit requirements, making it an excellent option for those who might not qualify for conventional loans.

What is a VA loan, and who qualifies?
A VA loan is a mortgage loan backed by the U.S. Department of Veterans Affairs, designed for military service members, veterans, and certain members of the National Guard and Reserves. It typically requires no down payment or private mortgage insurance (PMI), making it a great option for those who qualify.

What is a USDA loan?
A USDA loan is a government-backed mortgage offered to homebuyers in rural and suburban areas. It requires no down payment and offers competitive interest rates. To qualify, buyers need to meet income and property location requirements, making it a great option for those looking to buy in rural areas.

What is a conventional loan?
A conventional loan is a mortgage that is not insured or backed by the federal government. These loans usually require a higher credit score and a larger down payment than FHA loans, but they come with more flexible terms and potentially lower mortgage insurance costs if you put down at least 20%.

What is a jumbo loan?
A jumbo loan is a type of mortgage that exceeds the conforming loan limits set by the Federal Housing Finance Agency (FHFA). These loans are typically used for luxury or high-value homes and require stricter credit and income qualifications. They also tend to have higher interest rates due to the larger loan amounts.

What is a fixed-rate mortgage?
A fixed-rate mortgage is a loan with an interest rate that stays the same throughout the life of the loan, typically 15, 20, or 30 years. This provides stability and predictable monthly payments, making it a popular choice for many homebuyers.

What is an adjustable-rate mortgage (ARM)?
An adjustable-rate mortgage (ARM) is a type of loan where the interest rate can change periodically based on market conditions. ARMs typically start with lower rates for the first few years and then adjust. While this can offer lower initial payments, it comes with more risk as rates can increase over time.

What is a renovation loan?
A renovation loan, like the FHA 203(k) loan, allows you to finance both the purchase of a home and the cost of repairs or renovations in one loan. This can be a great option if you want to buy a fixer-upper and make improvements to it, as it allows you to finance the project upfront.

"I educate first-time homebuyers so they can make informed decisions"
Said Hamood - Seattle Mortgage Broker - NMLS#1827048
Said Hamood | NMLS #1827048 | Barrett Financial Group, L.L.C. | NMLS #181106 | 275 E Rivulon Blvd, Suite 200, Gilbert, AZ 85297 | TX view complaint policy at www.barrettfinancial.com/texas-complaint | WA MB-181106 | Equal Housing Opportunity | This is not a commitment to lend. *All loans are subject to credit approval. | mlsconsumeraccess.org/EntityDetails.aspx/COMPANY/181106